
 (503) 747-6534
 Client Login
 Search

 By
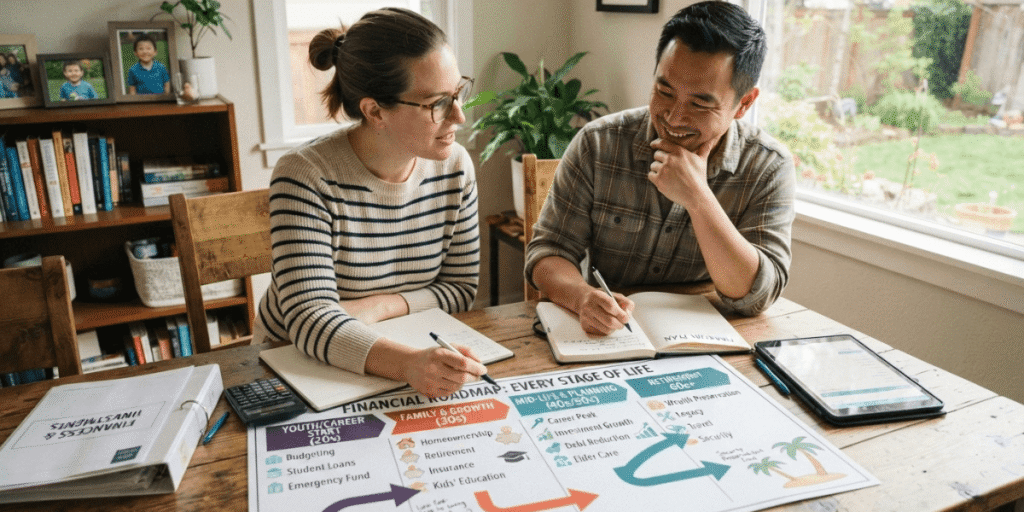
A financial roadmap connects your income, savings, debt, and goals in a coordinated plan that can evolve throughout your life. Reviewing your priorities as your career, family, and circumstances change can help you make informed decisions while staying focused on long-term goals.
Financial priorities rarely stay the same. What matters in your twenties may look very different from what matters in your fifties or during retirement.
A financial roadmap provides structure for those changes by connecting today’s financial decisions with the goals you want to achieve in the years ahead.
What a Financial Roadmap Includes
A financial roadmap goes beyond a monthly budget. It brings together income, expenses, savings, debt, insurance, investments, and long-term goals so you can see how each part of your financial life fits together.
Start by assessing where you are today. Review your income, spending, savings, investments, and outstanding debt, then identify what you want to accomplish. Putting those details in writing can make it easier to identify priorities and track your progress.
Financial Priorities at Different Stages of Life
Everyone’s circumstances are different, but certain financial priorities commonly become more important at different stages.
Your 20s: Building a Foundation
Early adulthood can be an important time to establish financial habits. Priorities may include building emergency savings, managing debt, establishing credit, and beginning retirement contributions.
Starting to invest for retirement early also provides more time for potential compound growth.
Your 30s: Balancing New Responsibilities
Career growth, marriage, children, and homeownership may introduce competing financial priorities. This can be a good time to revisit retirement contributions, insurance needs, emergency savings, and education planning if you have children.
Your 40s: Reviewing Your Progress
As income and responsibilities change, your forties can provide an opportunity to assess whether retirement savings and other long-term goals remain on track.
Reviewing debt, insurance coverage, investments, and future expenses can help identify areas that may need adjustment.
Your 50s: Preparing for Retirement
Retirement planning often becomes more detailed during this stage. You may begin estimating retirement expenses and income needs, reviewing Social Security considerations, and evaluating whether your investment strategy still reflects your timeline.
Eligible individuals can also make additional catch-up contributions to certain retirement accounts beginning at age 50.
Your 60s: Making Retirement Decisions
As retirement approaches, decisions about Social Security, Medicare and other healthcare coverage, retirement income, and portfolio withdrawals become increasingly important.
Planning how different income sources will work together can help create a more coordinated transition into retirement.
Retirement: Managing Income and Your Financial Plan
Once retirement begins, priorities often shift from accumulating savings to managing income, investments, taxes, and spending.
This can also be an appropriate time to review estate planning documents, beneficiaries, insurance needs, and plans for future healthcare or long-term care expenses.
How to Create Your Financial Plan
The basic planning process remains similar regardless of your age:
| Step | Action | Purpose |
|---|---|---|
| 1 | Review income, expenses, savings, and debt | Establish your starting point |
| 2 | Define short-, medium-, and long-term goals | Give your plan direction |
| 3 | Build or review emergency savings | Prepare for unexpected expenses |
| 4 | Establish savings and investment targets | Connect your money to specific goals |
| 5 | Review and adjust the plan regularly | Keep it aligned with your life |
Why Your Financial Plan Should Change With You
Using the same financial strategy throughout your entire life may not reflect changing goals, responsibilities, or timelines.
For example, someone early in a career may have decades to invest for retirement, while someone approaching retirement may be more focused on income needs, taxes, healthcare, and managing investment risk.
Consider reviewing your financial plan periodically and after significant events such as marriage, divorce, the birth of a child, a career change, home purchase, or retirement. These reviews provide an opportunity to adjust your savings, investments, insurance, and other priorities as circumstances change.
Frequently asked questions
A financial roadmap is a coordinated plan that connects your income, spending, savings, debt, investments, insurance, and long-term goals. It provides a framework for deciding how today’s financial choices support future priorities.
Start by reviewing your current finances and defining specific short-, medium-, and long-term goals. From there, establish priorities for saving, debt repayment, investing, insurance, and other financial needs.
Review the plan periodically and adjust it as your circumstances change.
Begin with a clear picture of your current financial position and the goals you want to achieve. Setting measurable targets, contributing consistently toward savings and investments, and monitoring your progress can turn broad goals into a more actionable plan.
Your plan should reflect your current responsibilities, goals, timeline, and financial circumstances. Retirement savings may be a major focus early in your career, while retirement income, healthcare, taxes, and estate planning may become more important later.
Consider reviewing your plan regularly and whenever you experience a significant change in your finances or personal life. A new job, marriage, divorce, birth of a child, inheritance, home purchase, or retirement may all warrant another look at your strategy.
Conclusion
A useful financial roadmap is not a plan you create once and leave unchanged. It should evolve as your career, family, finances, and priorities change.
The process remains relatively consistent: understand where you are, define where you want to go, create a strategy for getting there, and periodically review your progress. Keeping your plan current can help turn individual financial decisions into a coordinated approach to your long-term goals.
Lifelong Wealth Management helps individuals and families develop financial plans that evolve through different stages of life. If you’re looking for a financial planner, our team can help you review where you are today, clarify your priorities, and develop a strategy for the years ahead.